

Digital wallets are becoming more than just a convenience; they’re increasingly part of everyday life. According to Juniper Research, cited by TechRepublic, global digital wallet users are projected to increase from 4.4 billion in 2025 to over 6 billion by 2030, an increase of approximately 35%.
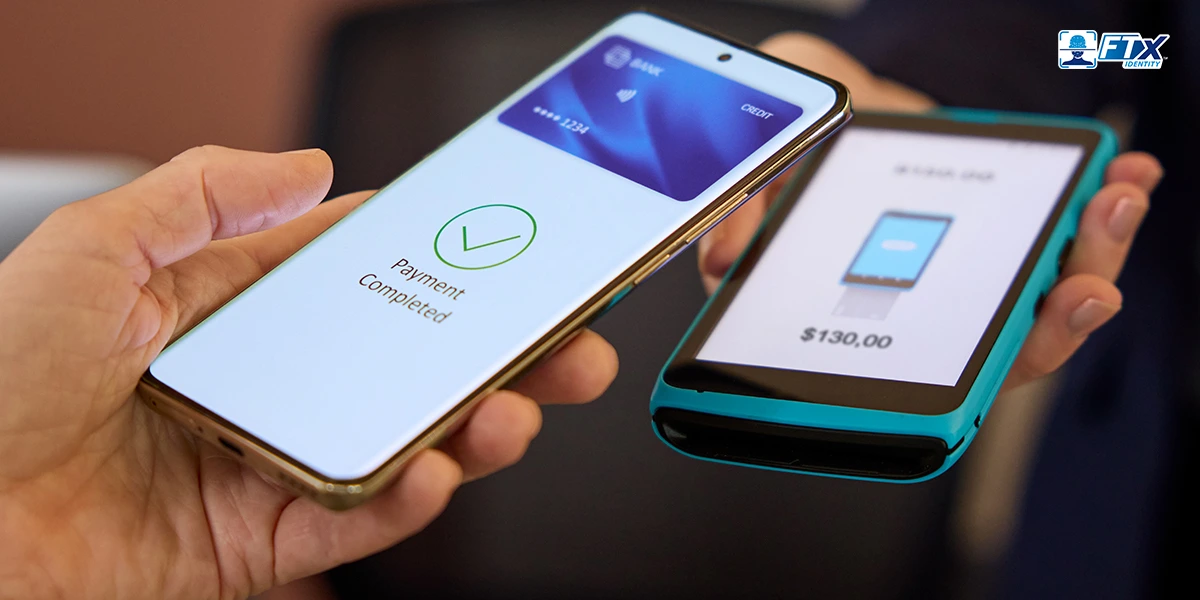
This growth is changing customer expectations at checkout. Shoppers like to tap to pay, pull up a loyalty card, or present an ID without digging through a physical wallet. Digital wallet technology can support all three, depending on the wallet and its features. But a digital wallet is no longer just a payment tool. Digital identity wallets and other supported wallet services can also hold or present identity credentials, such as mobile driver’s licenses, creating additional use cases for age verification, onboarding, and fraud prevention.
In this guide, we cover how digital wallets work, the main types, key security risks, where digital identity wallets fit, and how to evaluate digital wallet integration for your business.
- Digital wallets are growing fast. Juniper Research projects global users will rise from 4.4 billion in 2025 to over 6 billion by 2030.
- The five common types of digital wallets are mobile payment, digital identity, cryptocurrency, closed-loop merchant, and multi-purpose wallets, each with different business uses.
- Digital wallet security risks can include stolen devices, account takeover, fake credentials, phishing, and impersonation. Appropriate safeguards, such as device authentication and credential validation, can help reduce these risks.
- Digital identity wallets can support use cases in age-restricted retail, ecommerce, financial services, and gaming, where fast and reliable identity checks are required.
- Evaluate any digital wallet integration based on payment and POS compatibility, identity and age verification, fraud detection, data protection, and scalability.

What Is a Digital Wallet?
A digital wallet is an app or digital service that lets users store or access payment credentials and other digital items, such as loyalty cards, tickets, and, where supported, identity credentials. Customers use supported wallet features to pay, share proof of identity, or confirm their age without carrying physical cards.
Let’s start with the basics: what exactly is a digital wallet?
A digital wallet is an application that enables users to make payments and access digital credentials or other stored items. Depending on the wallet, it may store or provide access to payment cards, loyalty cards, tickets, and identity credentials.
In short, it empowers customers to make payments or verify their identity without the burden of physical cards. By simply inputting and storing credit cards, debit cards, driver’s licenses, or bank account details, they can seamlessly utilize their digital wallet on their device for purchases or identification verification.
A digital wallet isn’t limited to storing the previously mentioned items; it can also manage a range of items, including gift cards, concert tickets, plane tickets, hotel reservations, and much more.
Mobile payments have been around longer than you might think. Coca-Cola introduced mobile phone-based vending machine payments in Finland in 1997, an early example of using a mobile device to pay for a purchase.
You could buy a soda just by sending a text—a small step in the evolution of mobile payments that are now commonplace!
How Does a Digital Wallet Work?
Digital wallets use different technologies to transmit payment information from a user’s device to a payment terminal or online checkout. For in-store payments, supported wallets may use technologies such as near-field communication (NFC) or QR codes. To initiate a payment, users typically unlock their device, select their payment option, and follow the prompts for the wallet and payment terminal.
The technologies employed by digital wallets and mobile devices include:
QR Codes
Mobile device cameras can scan quick response (QR) codes, which are matrix barcodes, to initiate a payment or access information. These QR codes are utilized for making payments through digital wallets.
When the customer transmits their payment information from their digital wallet using the methods mentioned, the POS terminal or card reader forwards the transaction details to the customer’s payment processor. Subsequently, the payment processor communicates with the relevant payment networks and financial institutions to authorize and complete the purchase.
Magnetic Secure Transmission (MST)
Smartphones equipped with magnetic secure transmission (MST) technology emit a magnetic signal designed to work with compatible card readers. When a digital wallet featuring MST is used near a compatible reader, the payment information is transmitted to the card reader.
Near-Field Communication (NFC)
Contactless payments primarily utilize NFC technology. NFC enables short-range communication between devices, such as smartphones and smartwatches, and compatible card readers and payment terminals, all without the need for physical contact.

Types of Digital Wallets You Should Know
There are different wallets for different kinds of requirements. The main types of digital wallets differ by what they store, who controls them, and where they work. Knowing the difference helps you decide which ones your business should support.
1. Mobile Payment Wallets
These wallets store credit and debit cards on a smartphone or smartwatch or another compatible device, such as Apple Pay and Google Pay. Customers tap to pay in store or check out online with a saved card. Tokenization can help protect the customer’s actual card number during a transaction.
2. Digital Identity Wallets
These wallets store verified identity credentials, such as a Mobile Driver’s License (mDL) or other digital ID. Customers can share proof of identity or age without handing over a physical card. Businesses need verification tools that can read and validate these credentials.
3. Cryptocurrency Wallets
Crypto wallets manage the keys that provide access to digital currencies. Hot wallets stay connected to the internet for easy use, while cold wallets are stored offline for extra protection. Custodial wallets are managed by a third party, and non-custodial wallets leave control with the user.
4. Closed-Loop and Merchant Wallets
A closed loop wallet works only with one brand or merchant, such as a coffee chain app balance or a store gift card. These wallets can encourage repeat visits by holding stored value, rewards, and offers, all in one place.
5. Multi-Purpose Wallets
Multi-purpose wallets combine payments, money transfers, bill pay, and sometimes shopping or identity features in one app. Examples include PayPal and certain super apps. They suit users who want one place for many financial tasks.
Digital Wallet Security Risks Businesses Should Consider
Digital wallet technology often includes security features such as encryption, tokenization, and device authentication. But no system is risk-free. Many threats target the people and devices around the wallet, not just the wallet itself.
Here is what to plan for.
Do not trust what appears on a customer’s screen. Validate that a digital credential was issued by a trusted source and has not been altered, then confirm that the person presenting it is the real holder.
1. Stolen or Compromised Devices
A lost or stolen phone can expose a wallet if it has weak screen protection. Strong device locks and biometric checks reduce the risk. Businesses should use appropriate verification measures to help confirm that the person presenting a digital identity credential is its rightful holder.
2. Account Takeover
Attackers use stolen passwords or hijacked phone numbers to break into wallet accounts and move funds or change settings. Multi-factor authentication and biometric checks can make account takeovers more difficult.
3. Fake or Manipulated Credentials
Fraudsters can try to present forged or altered digital credentials. Businesses need to verify that a credential was issued by a trusted source and has not been changed, instead of trusting what appears on screen.
4. Social Engineering and Phishing
Fake messages and websites trick users into sharing wallet logins or one-time codes. This attack targets human trust, not technology. Customer education and clear security messaging help reduce these risks.
5. Identity Impersonation
Someone may use another person’s wallet details, or a deepfake, to pass as that person. Where supported, biometric matching and liveness detection can help confirm that the person presenting a credential matches the identity being verified and is physically present.
Where Digital Identity Wallets Could Be Used
Can a digital wallet prove your age? Yes, when it holds a verified digital ID and your business can validate it. Some formats let customers share only that they meet the age requirement, without revealing a full birthdate.
Digital identity wallets are still emerging, but their potential uses are becoming clearer. Any business that must confirm who a customer is, or how old they are, can benefit from a verification process that fits its needs and applicable requirements.
1. Age-Restricted Retail
Stores selling tobacco, vape, alcohol, and CBD must verify age as required by applicable laws. A digital ID can help confirm that a customer is old enough, and some formats let the customer share only that they meet the required age threshold instead of a full birthdate.
2. Ecommerce
Online sellers can use wallet-based credentials to check a customer’s age and identity at checkout or delivery. This can provide a stronger age-checking process than a simple age pop-up, which does not independently verify age, and may help reduce fraud from stolen or fake identities.
3. Financial Services
Banks and fintechs can use digital credentials to support customer onboarding and meet Know Your Customer (KYC) requirements. Reusable verified identities may reduce repetitive form filling and make the signup process easier for customers.
4. Gaming and Gambling
Operators must confirm age and identity before a player can wager, where required by law. Digital identity wallets can support fast, reliable checks at signup and help keep underage users off the platform.
Are Digital Wallets Safe?
To put it simply, yes.
Digital wallets incorporate a security feature called tokenization, a process that replaces sensitive, encrypted data with non-sensitive digital equivalents, or tokens.
Whenever a user initiates a payment, the digital wallet generates a unique, one-time token comprising random numbers. Only the merchant’s payment gateway can match this token to process the payment.
The combined use of encryption and tokenization renders information useless and indecipherable to fraudsters. Even in the event of a retailer being hacked, a customer’s payment details remain safeguarded due to the multiple layers of protection.
Compared to using a physical card’s chip or magnetic stripe, digital payments are generally considered more secure, not only because of tokenization but also due to the added requirement for authentication. If a physical card is stolen, it’s relatively easier for unauthorized use.
However, digital wallets typically offer additional layers of security, such as fingerprint scans, facial recognition, or password protection, further fortifying the safety of transactions.
Benefits of Embracing Digital Wallets for Businesses
While the terms “easy” and “quick” are often associated with digital wallets, it’s important to highlight the distinct advantages they bring to businesses.
- Enhanced Customer Experience: Digital wallets provide a user-friendly and convenient payment method. Customers appreciate the ease of use and the ability to manage their payments digitally. This convenience can contribute to a better customer experience.
- Faster Transactions: Digital wallets can help speed up transactions. With just a few taps on a smartphone or a click of a button, payments can be made swiftly, helping reduce checkout times. This can benefit both customers and businesses, especially during peak shopping periods.
- Increased Security: Digital wallets can use security measures, such as encryption, tokenization, and biometric authentication, to help protect sensitive payment information. These measures can reduce certain fraud risks, although they do not eliminate them.
- Higher Conversion Rates: Due to the convenience of digital wallets, businesses may see improved conversion rates. When the payment process is quick and hassle-free, customers are more likely to complete purchases, depending on the overall checkout experience.
- Reduced Operational Costs: Digital wallets can potentially reduce operational costs for businesses. Handling physical cash or maintaining traditional payment systems often incurs additional expenses. Depending on the payment methods used, digital wallets may reduce some cash-handling tasks and related costs.
- Improved Customer Loyalty: The positive experience of using digital wallets can contribute to enhanced customer loyalty. Businesses that offer convenient payment methods may encourage repeat visits from customers who appreciate the efficiency and ease of using these platforms.
- Global Accessibility: Digital wallets can help businesses cater to a broader audience, including international customers. However, availability depends on the wallet provider, supported markets, currencies, and payment infrastructure.

How Businesses Should Evaluate Digital Wallet Integration
Successful digital wallet integration depends on how well a wallet fits your existing systems and customers. Whether you build a digital wallet as a service platform or choose off-the-shelf digital wallet solutions, compare digital wallet features against these ten factors.
1. Payment Compatibility
Check that your payment processor supports the wallets your customers use, including Apple Pay and Google Pay. Gaps here can lead to declined payments and lost sales.
2. POS Compatibility
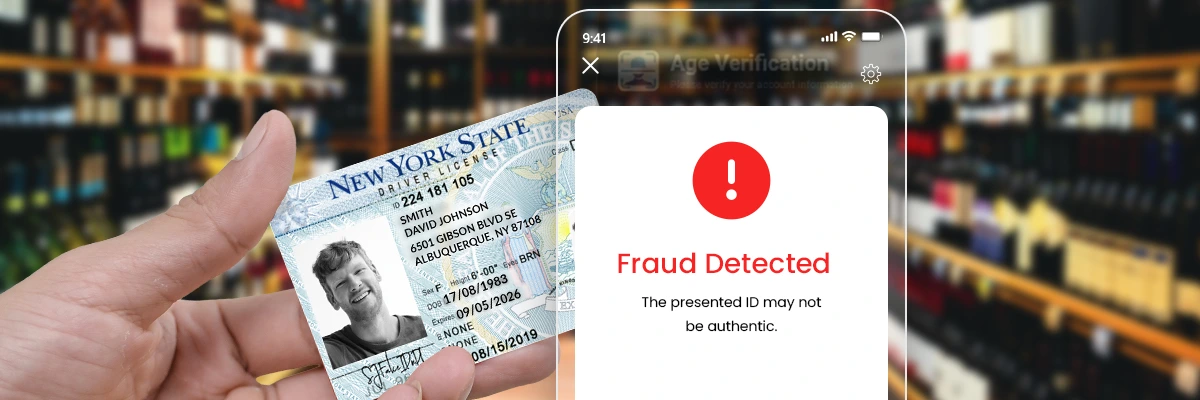
Your point-of-sale hardware and software should accept contactless and wallet payments, and ideally digital IDs. Confirm which payment and identity-verification capabilities your POS system supports, as accepting wallet payments does not automatically mean it can validate digital IDs. Confirm your terminals support NFC and QR code payments where needed.
3. Ecommerce Integration
Wallet buttons should work smoothly for an online checkout on both desktop and mobile. A one-tap option can reduce checkout friction and make it easier for customers to complete purchases.
4. Identity Verification
If you accept digital IDs, you need a way to validate that the credential is genuine and unaltered. Look for tools that verify the issuer and help confirm that the credential belongs to the person presenting it.
5. Age Verification
For age-restricted products, confirm the system can check age from a digital ID and support any recordkeeping required by applicable laws and your compliance procedures. This can help with compliance and audits.
6. Fraud Detection
Look for risk scoring, device checks, and monitoring for unusual activity. Layered fraud tools can help identify more potential issues than relying on a single check.
7. Data Protection
Ask how customer data is encrypted, stored, and shared. Choose providers that follow applicable PCI DSS (Payment Card Industry Data Security Standard) requirements and respect privacy laws that apply to your customers.
8. Customer Experience
The process should feel fast and simple for both customers and staff. Test it yourself. If the process is confusing or adds unnecessary steps, customers will notice.
9. Omnichannel Support
Customers should have a consistent experience in store, online, and in your app. Payment, loyalty, and identity data should work across every channel where the relevant systems and features are supported.
10. Scalability and Interoperability
Choose solutions that grow with your business and work with other systems through open standards. This can help reduce dependence on one vendor as wallet types and regulations change.
Conclusion
Digital wallets are becoming an increasingly popular payment option, offering convenience for everyday purchases and other transactions. From contactless payments to ID acceptance, their features are changing how businesses handle payments and identity checks. For businesses, supporting the right wallet options can improve the customer experience, add layers of security, and help reach more customers.
Ready to accept digital IDs and wallet-based credentials with confidence? See how FTx Identity verifies age and identity in seconds, in store and online. Request a free demo today.